7 Tax Deductions You Can Write Off as a Realtor
As a realtor, knowing which tax deductions you can claim is a game-changer for your finances. You can write off important expenses like your self-employment taxes, vehicle costs (whether you use mileage or actual expenses), and marketing efforts—from yard signs to digital ads. These write-offs help lower your taxable income and keep more money in your pocket.
Don’t forget about home office deductions if you work exclusively from home. Licensing fees and ongoing education costs also qualify as deductible expenses.
Plus, you can deduct retirement contributions and health insurance premiums, which are great perks for self-employed realtors.
Keeping detailed records is key to maximizing your savings. And getting professional advice can make a big difference in how much you save.
Explore these tips to boost your tax benefits this year and take control of your real estate business finances!
Key Takeaways
– Deduct vehicle expenses using either the standard mileage rate of 67 cents per mile or actual vehicle costs based on business use.
It’s a great way to save money if you’re driving a lot for your real estate business.
– Claim home office deductions using the simplified $5 per sq ft method or actual expenses for exclusive real estate workspaces.
This means if you have a dedicated space just for your work, you can write off some of those costs.
– Write off marketing costs including advertising, signage, client gifts up to $25, and digital marketing tools like CRM and website hosting.
Marketing is essential, so don’t forget to deduct these expenses—they really add up.
– Deduct licensing fees, ongoing education, and training expenses necessary to maintain or improve real estate skills.
Keeping your skills sharp isn’t just good for business, it’s good for your taxes too.
– Reduce taxable income by deducting retirement plan contributions and health insurance premiums for yourself and dependents.
Planning for the future and taking care of health costs can both lower what you owe come tax time.
Self-Employment Taxes for Realtors Explained
Because realtors are classified as statutory nonemployees, you’re considered self-employed for federal tax purposes and must pay self-employment tax on your earnings. This tax, which totals 15.3%, covers Social Security and Medicare.
Realtors pay 15.3% self-employment tax covering Social Security and Medicare as statutory nonemployees.
When tax season rolls around, you’ll report your income and expenses on Schedule C. Keeping accurate records of your expenses and mileage is essential since these can become important tax deductions that lower your taxable income.
As a self-employed realtor, you’re responsible for calculating and paying estimated quarterly taxes to avoid penalties. Understanding how self-employment tax works and what expenses qualify as deductions helps you stay compliant and maximize your savings.
Stay organized throughout the year, so you’re ready to handle your tax obligations efficiently and keep more of what you earn.
Tracking Business Expenses for Real Estate Agents
Managing your business expenses carefully helps you make the most of the deductions available to you as a self-employed realtor. To do this, keep detailed records of all business expenses, including receipts, invoices, and bank statements.
Use a dedicated business account or credit card to separate personal and professional transactions. This makes recordkeeping a lot simpler.
For mileage, maintain a daily mileage log with the date, destination, purpose, and miles driven. This will support your tax deductions and keep things clear.
Regularly export and organize your expense reports, especially before tax season. That way, you can make sure nothing gets missed.
Be sure to document all deductible costs, like marketing, licensing, home office, and travel expenses. It helps strengthen your claims.
Consistent expense tracking and thorough recordkeeping make it easier to maximize your tax deductions. Plus, it helps you avoid headaches during an audit.
Vehicle Expense Deductions for Realtors: Mileage vs. Actual Costs
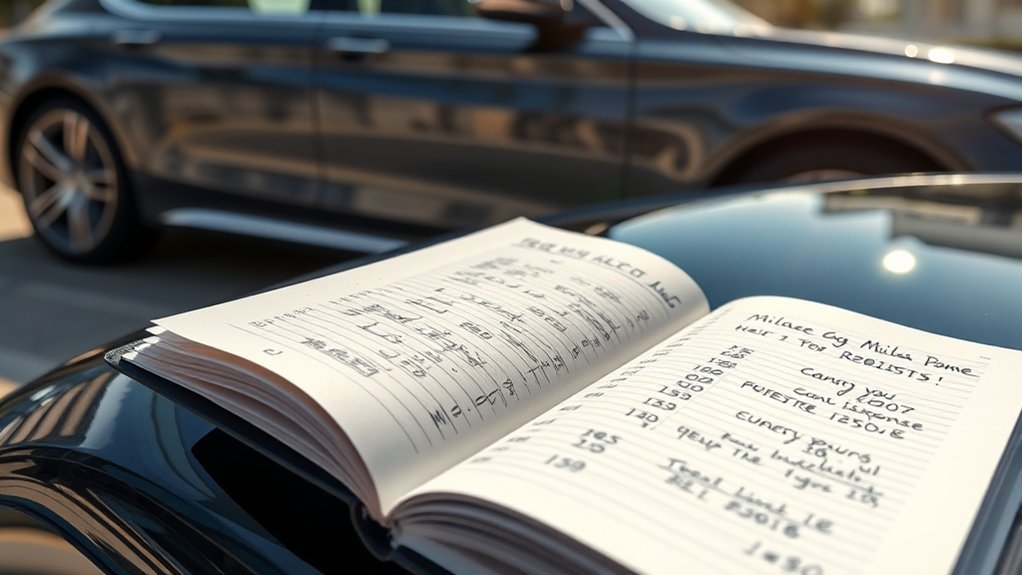
When you use your vehicle for real estate business, you have two main options to deduct your vehicle expenses: the standard mileage method or the actual expense method. The mileage deduction lets you multiply your business miles by the 2024 standard mileage rate of 67 cents. It’s simple and preferred if you drive a low-cost vehicle or rack up many business miles.
Alternatively, the actual expenses method requires you to track all vehicle costs like gas, repairs, and insurance. Then, you apply the business use percentage to find your deductible amount.
Whichever method you choose, keep a detailed mileage log recording dates, destinations, miles, and purpose. Remember, once you pick a method, you must use it consistently in future years unless the IRS permits switching under specific conditions.
Marketing and Advertising Deductions for Real Estate Agents
Although marketing efforts can vary widely, you can deduct many expenses that directly support promoting your real estate business. Marketing expenses like signage, promotional flyers, and business cards are fully deductible, helping you showcase listings and build your brand.
You can also write off advertising deductions for online ads on platforms such as Facebook, Instagram, and Google, especially when they promote listings or increase brand awareness. Don’t forget client gifts related to marketing, like branded items or giveaways, up to $25 per person.
Digital marketing tools, including software subscriptions for CRM, email campaigns, and website hosting, qualify as deductible expenses too. By tracking these costs, you can reduce your taxable income while effectively marketing your real estate services.
Home Office Deductions Realtors Should Know
You can choose between the simplified and regular methods when claiming home office deductions. The simplified method offers a straightforward $5 per square foot deduction, while the regular method lets you deduct actual expenses based on your business-use percentage.
Just remember, your home office must be used exclusively and regularly for your real estate work to qualify. It’s important to keep that in mind so you don’t run into any issues with the IRS.
Simplified Versus Regular
Deciding between the simplified and regular home office deduction can really impact your tax savings as a realtor. The simplified method lets you claim $5 per square foot of your dedicated home office space, up to 300 square feet, without having to track detailed expenses.
On the other hand, the regular method means you’ll calculate your actual business expenses like mortgage interest, utilities, and repairs. Then, you apply your office’s business use percentage to those costs.
Here are some things to think about when choosing the best deduction:
The simplified method is super easy and doesn’t require you to keep track of every little expense. But the regular method might get you a bigger deduction if your business expenses and office size are pretty substantial.
Just remember, both methods need you to use your home office exclusively for business activities.
Knowing these options will help you maximize your home office deduction the right way.
Exclusive Business Use
When claiming a home office deduction, the space must serve your real estate business exclusively and regularly. This means you can’t claim areas also used for personal activities.
To qualify, your home office must be your principal place of business, even if you work elsewhere occasionally. You can calculate your deduction using the simplified method—$5 per square foot up to 300 square feet—or the regular method, which involves tracking actual expenses like mortgage interest, utilities, and insurance.
With the regular method, you apply the business-use percentage based on your home office’s square footage compared to your whole home. Remember, exclusive use is key; spaces with dual purposes won’t qualify.
Licensing and Education Deductions for Real Estate Agents
You can deduct licensing fees, including initial costs and renewals, as part of your business expenses. Education expenses like courses, certifications, and industry seminars also qualify if they help you maintain or improve your skills.
Just make sure to keep detailed records to support these deductions when filing your taxes. It’s really important to have everything organized in case you need to prove it later.
Licensing Fees Deductible
Although managing your real estate license involves ongoing costs, many of these licensing fees are fully deductible as business expenses. You can write off licensing fees paid to state or local authorities, including license renewal costs and required background checks.
Continuing education expenses necessary to keep your real estate license current also qualify as deductible expenses. To maximize your tax deductions, maintain detailed record keeping of all related costs.
Here are common deductible licensing fees:
- License renewal fees and required background checks
- Continuing education courses and industry certifications
- Dues to real estate associations and MLS memberships
Education Expense Claims
Since maintaining your real estate license requires ongoing education, you can deduct expenses for licensing renewal fees, continuing education courses, and industry certifications directly related to your business.
Education expenses such as training seminars, workshops, and professional development materials improve your skills and qualify as deductible costs.
Remember, pre-licensing courses aren’t deductible, but post-licensing and renewal education are.
Keep all receipts for educational materials and training expenses to support your tax deductions.
| Expense Type | Deductible? | Notes |
|---|---|---|
| Licensing Renewal Fees | Yes | Required to maintain license |
| Continuing Education | Yes | Includes courses & certifications |
| Pre-licensing Courses | No | Not deductible |
Maximize your deductions by tracking all relevant education expenses carefully. It really pays to stay organized!
Retirement and Health Insurance Deductions for Realtors
When managing your finances as a self-employed realtor, taking full advantage of retirement and health insurance deductions can substantially reduce your taxable income. You can deduct health insurance premiums for yourself, your spouse, and dependents, lowering your taxable income as an adjustment to income.
Plus, contributing to retirement plans like a SEP-IRA or solo 401(k) offers significant tax savings, with limits up to $69,000 in 2024. Keep in mind, deductions for health insurance depend on your net profit, so planning is key.
To maximize your deductions, focus on:
- Deductible health insurance premiums for you and your family
- Retirement contributions through SEP-IRA or solo 401(k)
- Consulting a CPA to optimize year-end tax deductions
Frequently Asked Questions
How Much Would a Real Estate Agent Make on a $300,000 House?
You’d make around $3,000 to $4,500 on a $300,000 house before expenses.
After brokerage splits, fees, and taxes, your net income could be much less. It really depends on your agreement and the market conditions.
What Is the Most Overlooked Tax Deduction?
The home office deduction is like a hidden treasure chest—you often overlook it. Don’t miss claiming your workspace, vehicle expenses, or education costs.
Keeping detailed records lets you access significant savings you might not realize you’re entitled to. It’s easier than you think to save some extra cash!
How Does the New $6000 Deduction Work?
The new $6,000 deduction lets you write off up to that amount for qualifying business expenses like home office costs or software.
You’ll need to keep good records and guarantee expenses are ordinary and necessary for your work.
It’s a great way to save money if you’re running a business or working from home. Just make sure you stay organized!
How Much Mortgage Interest Can I Deduct?
You can deduct mortgage interest on loans up to $750,000 if taken after December 15, 2017. For older loans, limits may differ.
Just make sure to itemize deductions and keep your payment records handy. It’s pretty straightforward once you have everything organized.
Conclusion
Now that you know these seven powerful tax deductions, imagine how much you could save by claiming them all. But don’t stop here—there’s more to uncover about maximizing your deductions and keeping your hard-earned money where it belongs.
Ready to take control of your finances and boost your bottom line? Dive deeper, stay informed, and watch your real estate career thrive like never before.
Remember, mastering tax deductions as a realtor isn’t just about saving money—it’s about smart financial planning that supports your growth. The next big saving might be just around the corner, so keep exploring ways to optimize your expenses and keep more of what you earn.